Figuring the Real Value of Organic Production for Your Vegetable Farm
 October 21, 2026
Organic produce isn’t losing its consumer. The more complicated question is whether the economy continues to work as well for the grower. U.S. organic food sales reached an estimated $70.1 billion in 2025, according to USDA’s Economic Research Service (ERS). Fresh fruits and vegetables have historically been the largest organic food category, accounting for 33% of U.S. organic food sales in 2024.
Yet domestic organic acreage has declined in recent years. USDA’s Organic Situation Report, 2025 Edition points to that contrast: Consumer demand remains strong, but fewer U.S. acres are being devoted to organic production.
Watch the Premium
Higher production costs are a familiar part of the organic equation. Richard Smith, retired University of California Cooperative Extension vegetable crop and weed science farm advisor, points particularly to fertilizer, weeding, and pest problems that can reduce yield.
That makes the premium critical: It has to compensate for those additional costs and risks. And USDA’s analysis suggests that premium is worth watching closely.
ERS examined terminal market prices for several high-value organic fruits and vegetables from 2015 through 2023. Organic apples, spinach, and strawberries continued to command higher prices than their conventional counterparts, but the size of those premiums trended downward.
The shift doesn’t necessarily mean consumers are turning away from organic. During the recent inflationary period, conventional produce prices increased faster in some cases, narrowing the gap between conventional and organic prices.
Lettuce illustrates how quickly the relationship can change. During the 2022 supply disruption caused by weather, pest pressure, higher input costs, and water shortages in California and Arizona, both conventional and organic lettuce prices climbed. But because conventional prices rose sharply, the organic premium for iceberg lettuce temporarily disappeared.
Smith says supply ultimately plays a major role in prices. Competition among organic growers and periods of overproduction can depress prices rapidly, followed by an adjustment as acreage and prices settle back toward more typical levels.
He recalls one major grower leaving organic production when the available premiums weren’t sufficient to cover costs. At the same time, he points out that many large vegetable companies continue to maintain sizable, robust organic programs.
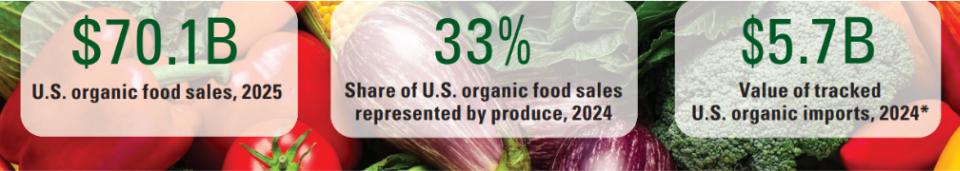
USDA added organic-specific trade codes over time, so the increase isn’t entirely attributable to greater import volume.
Where You Grow Matters
Smith’s experience is primarily with larger Salinas Valley organic operations supplying major retail outlets, and he cautions that smaller organic growers selling into local markets may have a different experience.
Geography can change the equation, too.
California has historically benefited from its ability to produce vegetables that competing regions could not, Smith says. But some of that advantage has eroded as transportation has become more expensive, and plant breeders have developed varieties capable of handling greater heat in regions once considered less favorable for those crops.
The result is a moving calculation for growers. Production costs, expected yield, pest pressure, available premium, location, and customer base all influence whether a crop makes sense organically.
Competition Doesn’t Stop at the Border
Domestic organic growers also compete in an increasingly global market.
The value of tracked U.S. organic imports reached $5.7 billion in 2024, according to ERS. Some of that growth reflects new organic-specific trade codes that allow USDA to identify previously untracked organic products. However, import values also rose among products USDA was already tracking.
For U.S. vegetable growers, the significance isn’t simply how much organic product enters the country, but where imported production competes directly with domestic crops.
Mexico has long held a cost and geographic advantage in supplying Eastern U.S. markets, Smith says. Lower production costs combined with proximity to those customers can put imported vegetables in direct competition with U.S.-grown product.
Events in 2026 disrupted that dynamic for some crops, particularly iceberg lettuce, and Smith expects growers and buyers to scrutinize sourcing decisions more closely as a result.
Organic also isn’t the only production claim competing for consumers interested in how their food is grown. USDA notes growing interest in other approaches, including regenerative agriculture, although unlike organic, “regenerative” does not have a USDA regulatory standard.
Demand alone doesn’t determine whether organic production works for a particular farm. The opportunity is where the premium, production costs, crop, location, and customer base still add up.
Subscribe Today For