Reasons Why There’s Cautious Optimism for Almond Crop Prices
 October 10, 2026
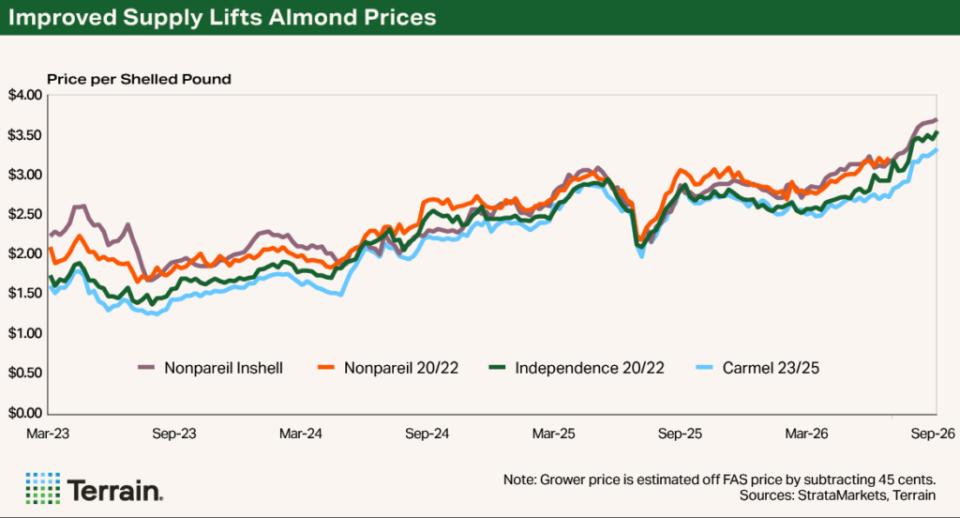
After years of low returns for almond farmers, crop prices have been moving in the right direction. While almond prices have not returned to levels that characterized the profitability of the 2010s, the industry is in a far stronger position today than it was just a few years ago.
Gross grower returns that averaged $1.40 per pound in 2022 — the recent low point — are likely to be somewhere in the $2.50-$2.70 per pound range for the 2025 crop.
SUPPLY IS MORE MANAGEABLE
Much of this improvement can be traced to a dramatically different supply situation. The Almond Board of California’s official carry-in for the 2026-2027 crop year stands at 471 million pounds, a manageable inventory level and a substantial improvement from the carry-ins exceeding 800 million pounds that weighed on the market not long ago.
The longer-term supply outlook is also evolving. For the first time since 1995, bearing acreage is in decline. How much acreage shrinks due to the Sustainable Groundwater Management Act (SGMA) remains uncertain. What is clear, however, is that California almond production is approaching a more defined ceiling than it has ever faced because acreage is unlikely to increase.
DEMAND IS STABLE OVERALL
Demand has been relatively stable, with total shipments down just 1% year over year (YOY), according to the Almond Board. Exports grew 3% YOY. Domestic shipments remain less encouraging, with monthly shipment volumes close to levels last seen in 2013.
There are a handful of possible explanations. One is that the current bout of inflation has pushed consumers away from a high-priced, discretionary item like almonds. At the same time, while almonds appear well positioned to fit the preferences of GLP-1 users, demand could be facing pressure in specific channels, such as confectionery.
Given stable overall demand and the growth potential in new export destinations, I am optimistic for the long term.
TWO FACTORS SUPPORT OPTIMISM FOR Q4
For the rest of 2026, there are two reasons to be optimistic.
First, the 2026 crop will be smaller than initially expected. Whereas most early estimates put the crop at around 2.7 billion pounds, estimates continue to be revised downward, with some as low as 2.55 billion pounds. In addition to lower yields, high temperatures just after bloom have resulted in small kernel sizes for many growers. Together, these developments imply less available supply for the 2026-2027 crop year, particularly for certain sizes.
Second, many buyers need to rebuild inventories. In recent years, price volatility and uncertainty encouraged a hand-to-mouth purchasing strategy. Though there has been and will continue to be pushback as prices rise, buyers also will need to meet demand in their local markets. Purchasing activity tied to replenishing inventories could provide additional support to prices.
Taken together, these factors suggest that supply-demand fundamentals will support current prices and possibly lead to some price gains in the final quarter of 2026.
For more analyses on almond crop prices and related infographics, visit Terrainag.com.
Subscribe Today For